What Is the Process to Buy a House in Malaysia Step by Step?
So, you're dreaming of owning a slice of paradise in Malaysia, perhaps a sleek condo overlooking the KL skyline or a quiet landed home nestled in a leafy suburb. It's a fantastic goal, but let's be honest, the journey to buying property as a foreigner here can feel like navigating a maze blindfolded. From state consent quirks to financing hurdles, it’s not always straightforward. This guide is here to untangle that process, offering you a clear, step-by-step roadmap based on real expat experiences.
Understanding Foreigner Property Ownership in Malaysia
First things first, let's manage expectations and lay out the ground rules. Malaysia generally welcomes foreign property ownership, which is brilliant, but it comes with its own set of unique regulations that can trip up the uninitiated. This isn't like buying a house back home in many Western countries; there are layers of approvals and specific types of properties you can – and cannot – purchase.
Minimum Purchase Price Requirements
This is often the first shocker for many expats. Malaysia isn't a free-for-all when it comes to property prices for foreigners. Each state sets its own minimum threshold for foreign property acquisition, and these figures can vary significantly. You can't just buy any property you fancy; it has to be above a certain value.
For instance, in the bustling heart of Kuala Lumpur, the minimum purchase price for foreigners is currently RM1 million. Head over to Selangor, and you might find different tiers depending on the property type and location. Johor, particularly with its proximity to Singapore, also has specific requirements, often mirroring or exceeding KL's threshold in certain areas. These thresholds are put in place to ensure that foreign investment doesn't inadvertently price out local buyers from more affordable housing segments. This means those charming, cheaper terraced houses you might eye in a local neighbourhood are often out of reach for foreigners. It’s a policy designed to protect local interests, and while it can be frustrating if your budget is tight, it’s part of the landscape here. Understanding the local nuances for each state is crucial, as what applies in Penang might not apply in Melaka. This is why getting familiar with Understanding the Minimum Foreign Property Purchase Price by State in Malaysia is a key early step.
Types of Property Foreigners Can Buy
While Malaysia generally allows foreigners to own property, it’s not a blanket approval for all types of property. There are specific categories that are usually open for foreign purchase and others that are strictly off-limits or highly restricted.
Most commonly, foreigners purchase stratified properties like condominiums, apartments, and serviced residences. These are typically in urban or desirable areas, often within integrated developments that offer a host of amenities. They are popular choices for expats due to their lifestyle offerings, security, and often, their location close to business districts and international schools.
When it comes to landed properties – think bungalows, semi-detached, or terraced houses – these are generally more restricted. While it's not impossible, particularly for high-value landed homes in certain designated zones, it’s significantly more complex and subject to stricter state consent and minimum price requirements. In many cases, landed properties might be part of a larger approved development, or they could fall under categories designated for local Bumiputera (indigenous Malays) ownership, which are entirely off-limits to foreigners. Malay Reserve Land, for example, is explicitly reserved for Malaysians of Malay descent and absolutely cannot be acquired by foreigners. It’s vital to verify the land title and any specific restrictions from the get-go to avoid heartache down the line.
Foreigners are also generally allowed to acquire commercial and industrial properties, but again, these come with their own set of regulations, and the intent here is typically investment or business operations, rather than residential living.
Essential Documents and Eligibility
Just like any major purchase, buying property in Malaysia as a foreigner involves a stack of paperwork. You'll need to demonstrate your identity, financial capability, and legal status in the country. The precise list can vary slightly depending on the state and the bank, but some core documents are universally required.
You’ll definitely need your passport, a valid visa (such as an Employment Pass, MM2H visa, or other long-term passes) to prove your legal residency. Employment letters, salary slips, and bank statements (both local and international) will be crucial for demonstrating your income and financial stability to the banks for mortgage applications. If you're self-employed, expect to provide audited financial statements for your business. You might also need a Letter of Offer from your employer, particularly if you're on an Employment Pass, as this helps substantiate your income and tenure in Malaysia. Be prepared for a comprehensive due diligence process, as banks are meticulous when it comes to foreign borrowers. You'll also need to be above the legal age of 18. Some states may have additional requirements, so always confirm with your chosen real estate agent and lawyer.
The Step-by-Step Purchase Process for Expats
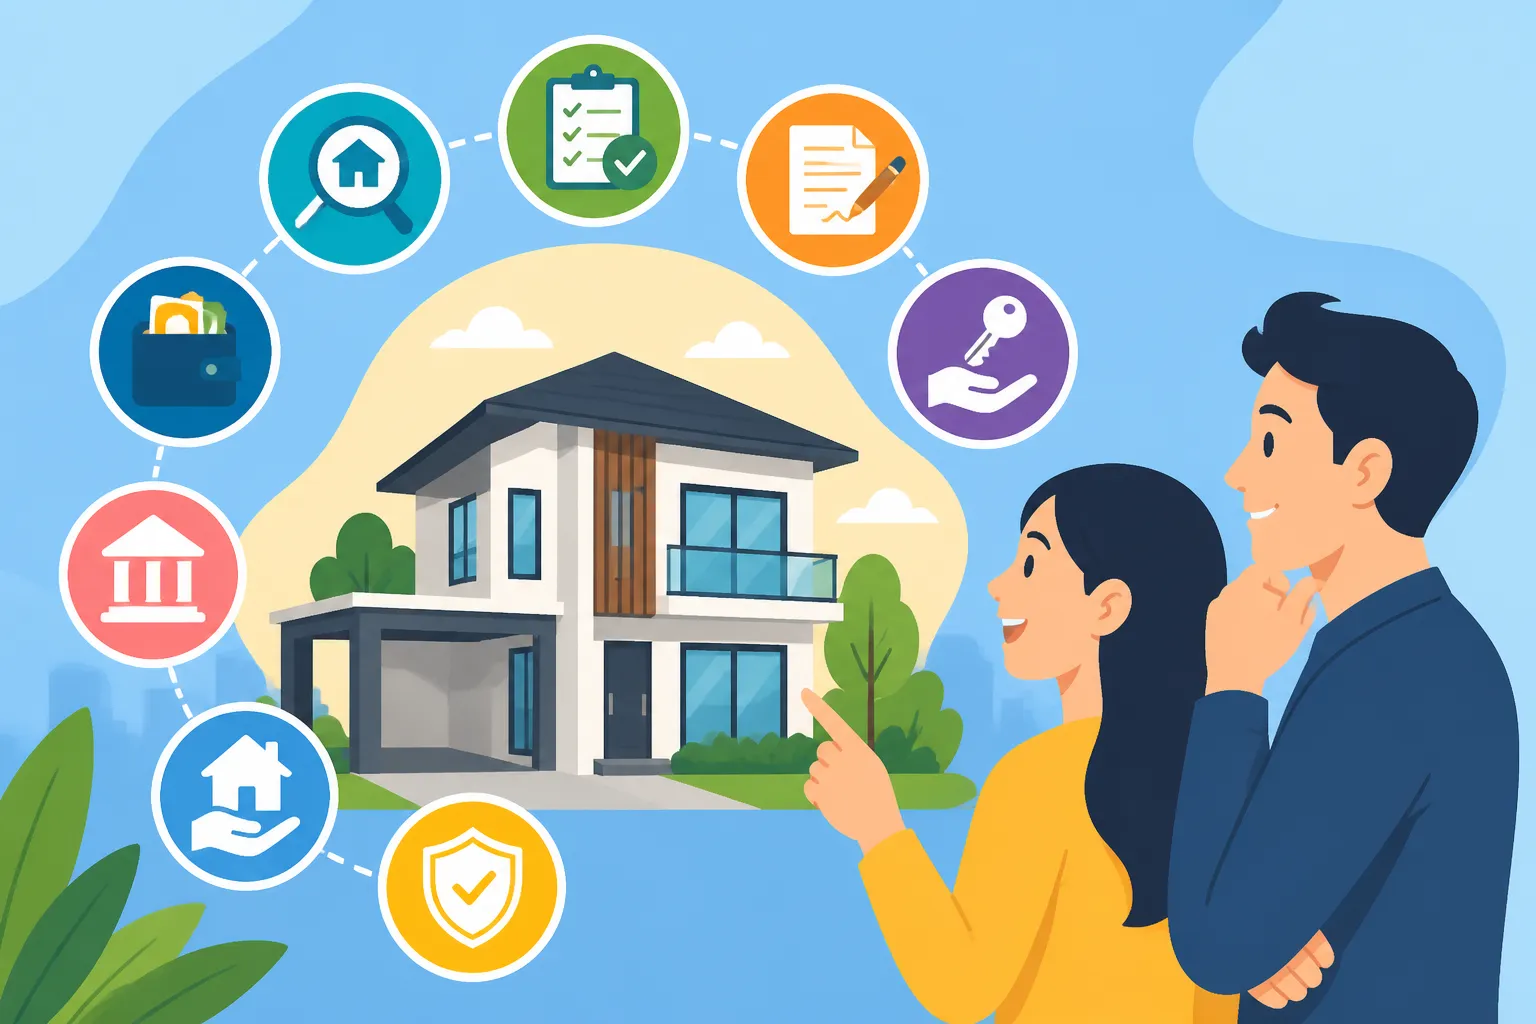
Alright, now that you've got a grasp of the basic rules, let's walk through the actual process. It’s a journey that requires patience, a good team, and a healthy dose of persistence. Expect it to take a few months, and be prepared for administrative delays – they are almost a rite of passage here!
Finding the Right Property and Agent
This is where the fun begins, or so they say! The quest for your dream home starts with serious research into locations, types of properties, and what fits your budget and lifestyle. Kuala Lumpur offers vibrant city living, while Penang brings island charm, and Johor Bahru provides strategic access to Singapore. Each area has its own flavour, pros, and cons regarding expat living, amenities, and property values.
Once you have a general idea, your next crucial step is to find a reputable real estate agent who specialises in assisting foreign buyers. Seriously, don't skimp on this. A good agent is worth their weight in gold, acting as your guide through the labyrinthine regulations. They’ll understand the specific state consent requirements, know which properties meet the foreigner minimum purchase price, and be able to communicate effectively in English. Websites like PropertyGuru and iProperty are excellent starting points for browsing listings, but an agent will give you access to properties not widely advertised and, more importantly, provide local insights. They can advise on neighbourhoods, property management, and even the nuances of negotiating. Don't be afraid to interview a few agents before committing; find someone you trust and feel comfortable with. Remember, staying connected with your agent, lawyer, and bank while navigating viewings and paperwork is crucial. You might find a local SIM card handy, or for immediate connectivity upon arrival, an eSIM from providers like Airalo can be a lifesaver. This flexibility helps you coordinate seamlessly, whether you're in the city or exploring properties further afield.
Obtaining State Authority Consent
This is arguably the most unique and often frustrating part of the process for foreign buyers in Malaysia. Unlike many countries where a direct transaction can occur, here, foreigners need to obtain formal consent from the respective state authority (the Land Office) to purchase property. This isn't just a formality; it's a deep dive into your eligibility and the property's compliance with state regulations.
Your lawyer will typically handle the application for state consent, but you’ll need to provide all the necessary documents, including your passport, visa, the Sale and Purchase Agreement (SPA), and various declarations. The processing time for state consent can range from a few weeks to several months, depending on the state and the complexity of the application. It can stretch out for a long time, so cultivate patience! This stage often involves a fee, which varies by state and property value, and it’s non-refundable, regardless of the outcome. Without this consent, the property transfer cannot proceed, even if all other aspects of the purchase are finalised. It’s a critical bottleneck, and any issues with your documents or the property itself can lead to significant delays or even outright rejection.
Securing Financing (Mortgage)
Unless you’re paying cash, securing a home loan as a foreigner in Malaysia is another significant hurdle. While Malaysian banks do offer mortgages to foreigners, the conditions can be tighter than for locals. Typically, banks will look for a strong credit history, a stable income, and a significant down payment.
The loan-to-value (LTV) ratio for foreigners is generally lower, often capped at 70% or 80%, meaning you’ll need to fund 20% to 30% of the property purchase price yourself. This is higher than for Malaysian citizens. You'll need to provide extensive documentation: employment verification, bank statements (both local and from your home country), income tax returns, and possibly even proof of assets. Major banks like Maybank, CIMB, and Public Bank do cater to foreign borrowers, but their criteria can differ. It’s advisable to speak with a few different banks to compare interest rates and eligibility. Your lawyer can also recommend banks that are more accustomed to dealing with foreign purchasers. The whole process of getting a home loan as a foreigner in Malaysia can be quite detailed, so looking into How to Get a Home Loan (Mortgage) as a Foreigner in Malaysia is highly recommended.
Legal Due Diligence and Agreements
This is where your lawyer truly shines. After you've identified a property and your offer has been accepted, the legal framework kicks in.
- Letter of Offer: This is the initial agreement between you and the seller, outlining the basic terms, purchase price, and earnest deposit (typically 2-3% of the purchase price). This deposit is usually non-refundable if you back out without valid cause.
- Sale and Purchase Agreement (SPA): Within a specified period (usually 14-21 days) after the Letter of Offer, your lawyer will draft the SPA. This is the main legal document, detailing all the terms and conditions of the sale, including the property description, payment schedule, timelines, and responsibilities of both buyer and seller. Review this document meticulously with your lawyer to ensure everything is in order and you understand every clause. This agreement is legally binding once signed by both parties.
- Loan Agreement: If you’re taking out a mortgage, you’ll also sign a separate Loan Agreement with your bank. This document outlines the terms of your financing, including interest rates, repayment schedules, and the bank’s rights.
Your lawyer's role includes conducting thorough due diligence on the property itself, checking for encumbrances, ensuring the seller has the legal right to sell, and verifying the property title. They are there to protect your interests, so don't hesitate to ask questions.
Stamp Duty and Other Fees
Beyond the purchase price, there are several significant costs associated with buying property in Malaysia. These often catch new buyers off guard, so it’s crucial to budget for them upfront.
Here’s a breakdown:
- Stamp Duty on SPA: This is a tax levied on the SPA and is calculated based on a tiered system according to the property value. For instance, the first RM100,000 might be 1%, the next RM400,000 at 2%, and anything above RM500,000 at 3-4%. You can refer to Understanding Stamp Duty on Property Purchases in Malaysia for more detailed calculations.
- Stamp Duty on Loan Agreement: Another stamp duty is imposed on your loan agreement, typically a fixed rate of 0.5% of the total loan amount.
- Legal Fees: Your lawyer will charge fees for drafting the SPA, the loan agreement, handling the state consent application, and facilitating the transfer of ownership. These are also often on a tiered scale based on property value.
- Real Estate Agent Fees: Usually 2-3% of the purchase price, but this is typically paid by the seller. However, confirm this in your agreement with the agent.
- Valuation Fees: Banks require an independent valuation of the property, for which you'll incur a fee.
- State Consent Fees: As mentioned, a non-refundable fee applies for the state authority consent application, varying by state and property value.
- Disbursements: These cover various administrative costs, such as stamp duties for documents, search fees at the Land Office, and registration fees.
It's common for these additional costs to add up to 3-5% (or even more, depending on stamp duty tiers and state consent fees) of the total property value, so factor them in from the very beginning.
Navigating the Financial and Legal Hurdles
The journey doesn't quite end once you've signed the last document and picked up the keys. There are ongoing financial and legal aspects to consider to protect your investment and ensure a smooth ownership experience.
Real Property Gains Tax (RPGT) for Future Sales
Something many foreign buyers forget to consider is the exit strategy. When you eventually decide to sell your property in Malaysia, you will likely be subject to Real Property Gains Tax (RPGT). This is a tax on the profit you make from selling your property. The rates vary depending on how long you've owned the property and whether you are classified as a resident or non-resident for tax purposes.
For foreigners, the RPGT rates can be higher than for Malaysian citizens, especially if you sell within the first few years of ownership. For example, if you sell within three years, the rate might be 30% of the net gain. After five years, the rate usually drops. It's crucial to understand these implications upfront. This isn't a "surprise tax" – it’s a planned one. So, when you're thinking about Understanding Real Property Gains Tax (RPGT) in Malaysia, factor it into your long-term investment planning. Keep meticulous records of all your purchase costs, renovation expenses, and legal fees, as these can be deducted to reduce your taxable gain.
Protecting Your Investment: Key Considerations
Owning a property is a long-term commitment, and protecting your investment is paramount.
- Property Insurance: Once the property is yours, obtaining comprehensive property insurance is non-negotiable. This typically covers fire, flood, and other structural damages. If you have a mortgage, your bank will definitely require you to have this in place.
- Maintenance Fees and Sinking Funds: If you've bought a stratified property (condo, apartment), you'll be liable for monthly maintenance fees and contributions to a sinking fund. These funds are crucial for the upkeep of common areas, security, and major repairs. Ensure you understand these costs and the management body's track record. A poorly managed building can quickly depreciate in value.
- Quit Rent and Assessment Tax: These are annual taxes payable to the state (quit rent) and local council (assessment tax). Your lawyer should clarify these during the purchase, and it's your responsibility to pay them annually to avoid penalties.
- Ongoing Property Management: If you're planning to rent out your property, or if you travel frequently, consider engaging a reliable property management company. They can handle tenants, repairs, and ensure your property is well-maintained.
The Importance of a Good Support Network
Navigating property purchase in a foreign land can be incredibly complex and stressful. You absolutely cannot do it alone. Building a strong support network of trusted professionals is not just helpful; it’s essential.
- Reliable Real Estate Agent: As mentioned earlier, a knowledgeable agent who understands foreign buyer requirements and speaks excellent English is your frontline. They’ll help you filter properties, negotiate, and guide you through the initial steps.
- Experienced Property Lawyer: Your lawyer is your legal shield. They will handle all the contractual aspects, title searches, state consent applications, and ensure all legalities are met. Choose a firm with a solid reputation for dealing with expat clients.
- Mortgage Broker/Banker: Finding a banker or mortgage broker who understands the intricacies of foreign income and residency statuses can significantly smooth the financing process.
- Relocation Services (Optional, but useful): If you're relocating your entire life, not just buying a house, a relocation service can help with everything from visa applications to school searches. Once your new home is secured, the next big step is the move itself. Comparing international moving companies can be a headache, but platforms like Sirelo can help you find reliable movers to bring your belongings to your new Malaysian abode. They can help reduce the stress of international logistics, allowing you to focus on settling into your new property.
Here's a quick overview of key documents for property purchase:
| Document Type | Purpose | Where It's Needed |
|---|---|---|
| Passport & Visa | Proof of Identity & Legal Residency | Agent, Lawyer, Bank, State Authority |
| Letter of Offer | Initial Agreement & Reservation of Property | Seller, Buyer, Lawyer |
| Sales & Purchase Agreement (SPA) | Primary Legal Contract for Sale | Seller, Buyer, Lawyer, Bank, Land Office |
| Loan Agreement | Contract for Mortgage Financing | Bank, Buyer, Lawyer |
| Employment Letter/Salary Slips | Proof of Income & Employment for Loan Application | Bank |
| Bank Statements | Financial Standing Verification | Bank |
| State Authority Consent Application | Formal Permission for Foreign Ownership | State Land Office (via Lawyer) |
| Property Valuation Report | Independent Assessment of Property Value for Loan | Bank (arranged by Bank) |
| Quit Rent & Assessment Tax Bills | Proof of Annual Property Tax Payments (for ongoing ownership) | Local Council, State Land Office |
It’s worth mentioning that while the thought of How to Buy Property in Malaysia as a Foreigner: The Full Guide (2027) might seem daunting, having these pillars of support will transform a potentially overwhelming experience into a manageable one. Also, consider the broader context of your living situation; if you’re trying to decide whether to buy or rent, resources like How Do I Choose Between Renting and Buying in Malaysia? can help you weigh your options before diving into ownership.
Ultimately, buying a house in Malaysia as an expat is a marathon, not a sprint. It demands careful planning, due diligence, and a thick skin for bureaucracy. But when you finally get those keys and step into your very own home in this vibrant country, all the effort will be worth it.
Disclaimer
The information provided in this guide is for general informational purposes only and does not constitute legal, financial, or real estate advice. While every effort has been made to ensure accuracy, regulations and policies in Malaysia are subject to change. Expats are strongly advised to consult with qualified legal professionals, real estate agents, and financial advisors in Malaysia to obtain specific advice tailored to their individual circumstances before making any property purchase decisions.