What Documents Do I Need to Open a Bank Account in Malaysia?
Ah, the Malaysian bank account quest! If you've been living here for a while, you know the feeling. You arrive in this beautiful, vibrant country, ready to embrace the expat life, only to hit a wall of paperwork and regulations when you try to do something as seemingly simple as opening a bank account. It can be incredibly frustrating and often feels like you're jumping through endless hoops. This comprehensive guide is here to walk you through exactly what documents you'll need, tailored for various expat situations, to make that journey a little less daunting.
Navigating the Initial Maze: Why Opening a Bank Account Feels Like a Quest
I've been there, staring blankly at a bank teller while they rattled off a list of documents I didn't even know existed. It’s enough to make you want to just stuff your cash under your mattress! But really, understanding why banks ask for so much can help you prepare better and avoid repeat trips to the branch.
The Regulatory Landscape: Why Malaysian Banks Are So Strict
Malaysia, like many countries, has stringent regulations when it comes to banking, especially for non-residents or new residents. This isn't just to make our lives difficult, I promise! It's primarily driven by global and local Anti-Money Laundering (AML) and Counter-Financing of Terrorism (CFT) policies. Known as 'Know Your Customer' (KYC) requirements, these rules mandate banks to verify the identity of their clients, understand the nature of their financial activities, and assess any potential risks.
For us expats, this often translates into a demand for more documents than we might be used to in our home countries. Banks want to be absolutely certain of who you are, where you live, and where your money comes from. They're looking for stability and legitimate sources of funds, which means proving your employment, your residential address, and your legal status in Malaysia becomes paramount. It can feel invasive, sure, but it's part of the global effort to combat illicit financial activities. So, while it's a pain, try to approach it with patience, knowing it's standard procedure.
Understanding Your Options: Account Types for Foreigners
Before you even start gathering your documents, it's a good idea to know what kind of account you're aiming for. Most expats will look for a basic savings or current (checking) account, but there are other options too.
- Savings Accounts: These are typically straightforward, offering a safe place to keep your money and earn a small amount of interest. They are great for day-to-day transactions and often come with a debit card.
- Current Accounts: Also known as checking accounts, these are designed for frequent transactions, bill payments, and may include chequebook facilities. They generally don't earn as much interest, if any, compared to savings accounts.
- Foreign Currency Accounts (FCA): Some banks, like Maybank and CIMB, offer FCAs where you can hold money in major foreign currencies (USD, GBP, EUR, AUD, SGD, etc.). This can be incredibly useful for expats who receive salaries in foreign currency or need to make international transfers frequently. It helps you avoid multiple conversion fees. However, these accounts might have higher minimum balance requirements or specific eligibility criteria.
- Joint Accounts: If you're here with a spouse, you might consider a joint account. This usually requires both parties to be present and provide their full set of documents.
When considering your banking needs, think about how often you'll be transferring money, whether you need access to foreign currencies, and if your employer has a preferred bank. Knowing this beforehand will help you ask the right questions and ensure you're setting up the most suitable account for your situation. It's all part of figuring out the complex system of The Expat Guide to Opening a Bank Account in Malaysia.
The Essential Checklist: Documents You Absolutely Need
Alright, let's get down to the nitty-gritty. This is the part that often causes the most headaches, but with a clear checklist, you can tackle it systematically. Remember, always bring originals and several photocopies of everything. Banks sometimes make their own copies, but it's better to be overprepared.
Your Core Identity and Visa Documents
These are your absolute non-negotiables. Without these, you won't even get past the first hurdle.
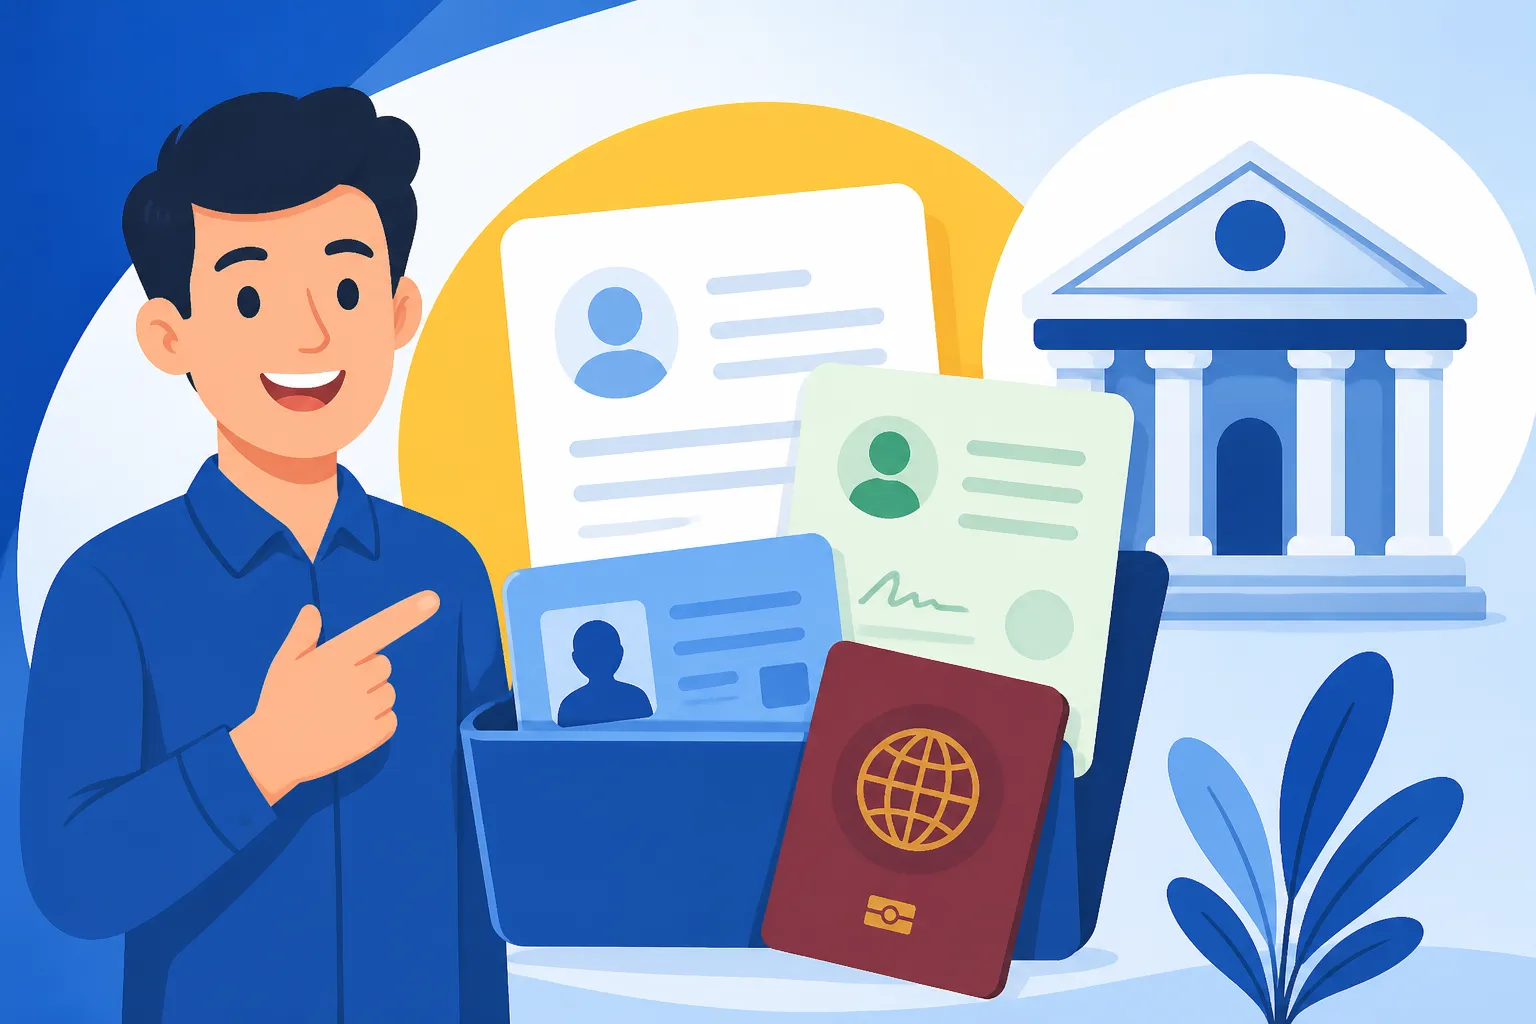
- Valid Passport: This is your primary form of identification. It must be current, with sufficient validity (often at least six months remaining). Ensure all pages, especially those with your personal details and visa stamps, are clear and readable. Banks will scrutinise this heavily. If you’ve recently renewed your passport, sometimes they want to see your old one too, especially if your visa is in it.
- Valid Malaysian Visa/Permit: This is arguably the most crucial document after your passport. Your legal right to reside in Malaysia directly impacts your eligibility for banking services.
- Employment Pass (EP): This is the most common for working expats. Ensure your Employment Pass endorsement in your passport is clear. Sometimes, the bank will also ask for your approval letter from the Immigration Department or Expatriate Services Division (ESD).
- Malaysia My Second Home (MM2H) Visa: If you’re an MM2H holder, your long-term social visit pass with the MM2H endorsement is key. Banks are generally more familiar with MM2H holders due to their specific financial requirements.
- Student Pass: For international students, this pass, along with a letter of acceptance or introduction from your educational institution, is vital.
- Dependant Pass: If you’re here as a spouse or child of an Employment Pass holder, your Dependant Pass, linked to the main pass holder, is required. The main pass holder may need to be present or provide additional supporting documents.
- Professional Visit Pass (PVP) / Long-Term Social Visit Pass: While less common for opening full-fledged bank accounts, some banks might accommodate, especially if you have a letter from a Malaysian company guaranteeing your stay and financial standing. However, for short-term passes like PVPs, it can be much harder to open a full account.
Always make sure your visa is current and has ample time remaining. Banks are hesitant to open accounts for individuals with visas nearing expiry.
Proving Where You Live: Address Verification
This is another big one. Banks need to confirm you have a physical address in Malaysia. A P.O. box simply won't cut it.
- Tenancy Agreement: If you're renting, your signed tenancy agreement is usually the go-to. It should clearly state your name, the property address, and the landlord's details. Make sure it's stamped by the Inland Revenue Board (LHDN) – this proves it's a legally registered agreement. Unstamped agreements might not be accepted.
- Utility Bills: Recent utility bills (electricity from TNB, water, or internet from providers like Unifi or Maxis) addressed to you at your Malaysian residence are excellent proof. The bill should ideally be less than three months old. If the utility bill is in your landlord’s name, you might need a letter from your landlord confirming your residence, along with a copy of their NRIC (MyKad) and the utility bill.
- Letter from Employer/University: Your employer can provide a letter confirming your employment and residential address in Malaysia. Similarly, a university can issue such a letter for students. This needs to be on company/university letterhead and signed by an authorised personnel.
- Correspondence from a Government Agency: Less common, but sometimes a letter from LHDN (Inland Revenue Board) or a local council addressed to your Malaysian address might work.
Providing multiple forms of address proof can strengthen your application, especially if one document seems insufficient.
Demonstrating Your Financial Standing: Income and Funds
Banks need to see that you have a legitimate source of income and funds, primarily for compliance and risk assessment.
- Employment Letter/Contract: A formal letter from your Malaysian employer, on company letterhead, stating your position, employment duration, and monthly salary is almost always required for Employment Pass holders. A copy of your employment contract also works.
- Recent Payslips: Usually, the last three months' payslips will be requested to corroborate your employment letter and demonstrate consistent income.
- Bank Statements (from home country/previous bank): To show your financial history and the source of funds you intend to deposit, banks might ask for recent bank statements from your home country bank or your previous bank, especially for initial deposits of larger sums. These can help satisfy the "source of wealth" requirement.
- Tax Identification Number (TIN) / Malaysian Income Tax Number: While not always mandatory at the point of opening, having a Malaysian income tax number or TIN is increasingly important, especially if you're a tax resident. You can get this from LHDN. It ties into your financial transparency and future tax obligations in Malaysia. If you're unsure about how to obtain one, there's a helpful guide on How to Register for an Income Tax Number with LHDN in Malaysia.
Don't be surprised if they ask for more than just one of these. The more transparent you can be about your finances, the smoother the process will likely be.
Additional Papers That Can Make or Break Your Application
Sometimes, the standard documents aren't enough, or an additional letter can simply make the process much easier.
- Letter of Introduction from Employer/University/Embassy: A strong letter from your employer or university introducing you to the bank, confirming your status, and even vouching for your character, can carry a lot of weight. For certain nationalities or high-net-worth individuals, a letter from your embassy might also be accepted.
- Reference Letter from Your Home Country Bank: A letter from your previous bank confirming your long-standing relationship and good standing can be beneficial, particularly if you’re trying to open a foreign currency account or have higher transaction limits.
- Malaysian Driving Licence: While not strictly for identification for banking, if you've managed to convert your foreign driving license to a Malaysian one, it can serve as a supplementary ID and proof of local presence.
- MM2H Approval Letter: For MM2H holders, the official approval letter from the Ministry of Tourism, Arts and Culture (MOTAC) or Immigration Department, which outlines your visa conditions and fixed deposit requirements, is a key supporting document. It also helps clarify your long-term residency status. You might also want to consult Understanding the MM2H Financial Requirements by State in Malaysia for specific details related to your region.
Gathering these supplemental documents, even if not explicitly requested initially, can often expedite the process and demonstrate your preparedness and genuine intent.
Tailoring Your Application: What Banks Expect from Different Expats
Malaysia attracts a diverse range of expats, and the banking requirements can subtly shift depending on your visa type and purpose of stay. What works for an Employment Pass holder might not be sufficient for a student or a digital nomad.
For the Employed: Employment Pass Holders
If you're in Malaysia on an Employment Pass (EP), you're generally in the most straightforward category. Banks are very familiar with EPs as they indicate stable employment and usually a good income.
The key here is demonstrating your legal employment and residency. You'll need:
- Your valid passport with the EP endorsement (Category I, II, or III)
- The official approval letter from the Malaysian Immigration Department or Expatriate Services Division (ESD) for your EP.
- A formal letter of employment from your Malaysian company, on company letterhead, stating your position, employment duration, and monthly salary. This is crucial for verifying your source of funds.
- Your most recent payslips (typically 1-3 months).
- Proof of residential address, such as a stamped tenancy agreement or utility bills in your name.
Some banks might even have special counters or relationship managers for expats from large multinational corporations (MNCs) that have corporate accounts with them. If your company is well-established, leverage that connection! For a deeper dive into this, check out How to Open a Bank Account on an Employment Pass in Malaysia.
Retirement and Long-Stayers: MM2H Visa Holders
The Malaysia My Second Home (MM2H) programme is designed for long-term stayers, retirees, and those seeking a second home here. MM2H visa holders generally find opening bank accounts relatively smooth, mainly because the visa itself requires a significant fixed deposit in a Malaysian bank, indicating financial stability.
Essential documents for MM2H holders include:
- Your valid passport with the MM2H endorsement (Long-Term Social Visit Pass).
- The MM2H approval letter from MOTAC or the Immigration Department.
- Proof of residential address in Malaysia (tenancy agreement, utility bills, or sometimes even a property purchase agreement if you've bought a home).
- For the initial fixed deposit, documentation proving the source of those funds, which you would have already provided during your MM2H application, might be requested again by the bank.
Banks like Maybank, CIMB, and Public Bank are accustomed to MM2H applicants and often have dedicated services. It's often easier for MM2H holders to open accounts and manage their finances, especially since they've already met stringent financial criteria for the visa itself. If you're wondering Can I Open a Bank Account as an MM2H Visa Holder?, the answer is usually a resounding yes, provided you have all your documents in order.
Students and Family Members: Dependant and Student Pass Holders
This category can be a bit trickier, as students and dependants often don't have their own independent income or primary visa.
For Student Pass holders:
- Your valid passport with the Student Pass endorsement.
- Official letter of acceptance or introduction from your Malaysian university/college, confirming your enrolment and course details. This letter should explicitly state that you are a student and sometimes even recommend opening an account for living expenses.
- Proof of residential address (hostel letter, tenancy agreement if living off-campus, or utility bill).
- Proof of funds, which might include bank statements from your home country, scholarship letters, or a letter of financial support from your parents/guardian.
For Dependant Pass holders:
- Your valid passport with the Dependant Pass endorsement.
- The passport and Employment Pass details of the primary pass holder (your spouse/parent). The primary pass holder might need to be present at the bank with you.
- Your marriage certificate (for spouses) or birth certificate (for children) to prove the relationship.
- Proof of residential address (often tied to the primary pass holder’s address).
- A letter of introduction or guarantee from the primary pass holder's employer might also be useful.
It can sometimes be challenging for dependants to open accounts independently without the primary pass holder's presence or extensive documentation. You might find some banks are more flexible than others, so it's worth inquiring at a few different institutions. If you have children on a dependant pass, you might be interested in details like Can My Children Study in Malaysia on a Dependant Pass?, which often involves similar documentation for their school enrolment.
The New Wave: Digital Nomads with DE Rantau Pass
The DE Rantau Digital Nomad Pass is a relatively new initiative, and while it's designed to attract remote workers, the banking landscape for them is still evolving. Digital nomads often work for foreign companies and might not have a Malaysian employer or traditional income proof.
For DE Rantau Pass holders:
- Your valid passport with the DE Rantau Pass endorsement.
- The official DE Rantau approval letter.
- Proof of consistent income from your foreign employer(s) or clients (e.g., recent foreign bank statements showing regular deposits, contracts with foreign clients, or letters from your foreign employer). This is critical for demonstrating financial solvency without a local employer.
- Proof of residential address in Malaysia.
- Your Tax Identification Number (TIN) from your home country, as you'll likely be paying taxes there, at least initially.
As this pass is newer, bank staff might be less familiar with it. You might need to patiently explain your situation and provide more comprehensive documentation regarding your foreign income. It's a journey, but it’s becoming increasingly common. For more details on the pass itself, refer to How to Apply for the DE Rantau Nomad Pass in Malaysia.
Beyond Approval: Managing Your Malaysian Finances
Once you've successfully opened your bank account, congratulations! You've cleared a major hurdle. But the financial journey in Malaysia doesn't end there. There are still considerations for managing your money effectively and staying compliant with local regulations.
Getting Your Money In and Out: Remittances and Transfers
One of the biggest concerns for expats is moving money across borders efficiently and cost-effectively. With your Malaysian bank account, you can now receive your local salary or transfer funds from overseas.
Traditional bank wire transfers are an option, but they can sometimes be slow and incur hefty fees, especially for smaller amounts. This is where modern remittance services truly shine. Companies like Wise (formerly TransferWise) have become incredibly popular among expats globally for their transparency, speed, and competitive exchange rates. They often use the mid-market exchange rate, saving you money compared to traditional banks. I've personally used Wise for years to send money back home and receive funds, and it's been a lifesaver.
Whether you're sending money home to family, paying off a mortgage in your home country, or receiving your salary from a foreign employer, exploring services beyond traditional banks can lead to significant savings. Make sure you understand the transaction limits and any reporting requirements for large sums. To further explore your options, read up on How to Transfer Money Into and Out of Malaysia as an Expat.
Staying Compliant: Understanding Local Tax Obligations
Having a Malaysian bank account also means you're firmly integrated into the local financial system, which brings with it tax obligations. Even if your salary is paid into a foreign account, if you are deemed a tax resident in Malaysia, your worldwide income might be subject to Malaysian tax.
Once your bank account is open, it's a good time to get your Malaysian Tax Identification Number (TIN) if you haven't already. This is crucial for filing your annual income tax returns with the Inland Revenue Board (LHDN). Depending on your length of stay and employment status, you might become a tax resident, which changes your tax rates and applicable reliefs. Understanding your tax residency status from the outset can save you a lot of trouble down the line. The 182-day rule is a significant factor in determining this, so do look into Understanding Tax Residency Rules for Expats in Malaysia (182-Day Rule).
Navigating the tax landscape can be complex, and many expats find it useful to consult with specialists or resources dedicated to Taxes for Expats in Malaysia. They can help you understand deductions, reliefs, and how to report foreign income correctly. Proper financial planning includes understanding your obligations to LHDN to avoid any penalties. For a comprehensive overview, consider delving into The Complete Guide to Taxes in Malaysia for Expats (2027).
Here’s a quick summary table of common documents, but always remember to confirm with your chosen bank as requirements can vary:
| Document Type | General Requirement | Specifics for Expats |
|---|---|---|
| Identity Proof | Valid Passport | Minimum 6 months validity, clear copy of personal details & visa pages. |
| Residency Proof | Valid Malaysian Visa/Permit (EP, MM2H, Student, Dependant, DE Rantau) | Endorsement in passport, accompanying approval letters. |
| Address Proof | Stamped Tenancy Agreement, Utility Bills (TNB, internet), Letter from Employer/University | Bills in your name (under 3 months old). If in landlord's name, add a support letter + landlord's NRIC. |
| Income/Funds Proof | Employment Letter, Payslips (3 months), Foreign Bank Statements, Scholarship Letter | Employer letter must detail position, salary, duration. Foreign statements for source of funds, especially for initial deposit. |
| Supplementary | Letter of Introduction (Employer/University), Home Country Bank Reference, MM2H Approval Letter | Employer intro letter on letterhead, signed. Bank reference for good standing. MM2H letter confirms programme participation and financial commitment. |
| Tax Info | Malaysian Tax Identification Number (TIN) | Increasingly requested; essential for tax residency and compliance. |
Once your bank account is set up, don't forget to activate online banking. It's a massive convenience for managing your accounts, paying bills, and transferring funds without having to visit a branch. Most Malaysian banks offer robust online and mobile banking platforms, and learning How to Set Up Online Banking with a Malaysian Bank should be high on your to-do list!
Disclaimer
Please note that the information provided in this guide is for general informational purposes only and is subject to change. Banking regulations and requirements in Malaysia can be updated by Bank Negara Malaysia (BNM) and individual financial institutions without prior notice. Always confirm the latest document requirements directly with your chosen bank before beginning the application process. We are not financial advisors, and this content should not be considered as such.