What Is the Difference Between EPF and SOCSO in Malaysia?
Navigating the administrative jungle of a new country is often one of the biggest headaches for any expat, and Malaysia is no exception. Among the many terms thrown your way when you start working here, "EPF" and "SOCSO" quickly become staples, often causing a fair bit of confusion. Are they the same thing? Do I, as a foreigner, even need to contribute? This guide is here to untangle the nuances of the Employees Provident Fund (EPF) and the Social Security Organisation (SOCSO), explaining their distinct roles, who contributes to what, and what it all means for your life and work here in Malaysia.
Unpacking EPF (Employees Provident Fund) in Malaysia
When you first hear about EPF, it’s usually in the context of retirement savings, and that’s precisely its primary mission. It’s essentially a compulsory savings scheme designed to help workers in Malaysia accumulate funds for their post-employment years. Think of it as your long-term nest egg, growing quietly in the background while you work.
What is EPF and its Core Purpose?
The Employees Provident Fund (EPF, or KWSP in Malay) is Malaysia’s national provident fund, established under the Employees Provident Fund Act 1991. Its core purpose is to provide a comprehensive social security savings scheme for members' retirement and to manage their savings in accordance with sound investment principles. For many Malaysians, their EPF account represents the single largest portion of their retirement savings, a lifeline for their golden years.
This isn't just about stashing money away; it's about financial security. The EPF aims to ensure that when you eventually stop working, you have a substantial lump sum to draw upon, helping you maintain a certain standard of living. It also allows for certain pre-retirement withdrawals, under very specific conditions, for things like housing, education, or even critical illness, which can be a huge relief in times of need. It’s a mandatory system that truly underpins the long-term financial stability of the workforce. If you're looking for a deeper dive into how this all works, check out our guide on Understanding the EPF and Retirement Savings System in Malaysia.
Who is Required to Contribute to EPF?
This is where it gets a little tricky for us expats. By default, EPF contributions are mandatory for all Malaysian citizens and permanent residents who are employed in the private sector. However, for non-Malaysian citizens, the rules are slightly different.
Foreigners working in Malaysia on an Employment Pass are generally not mandatory contributors to EPF. This means your employer doesn't have to contribute for you, nor are you required to contribute from your salary. However, and this is a big "however," an employer can choose to make EPF contributions for their foreign employees, and a foreign employee can also choose to contribute voluntarily. If either party opts in, then the contributions become legally binding. Many multinational companies (MNCs) and even some local companies offer EPF as an added benefit to attract and retain expat talent, making it a valuable perk. If you're wondering about the specifics, you might find our article Do Foreign Workers Contribute to EPF in Malaysia? particularly helpful.
How are EPF Contributions Calculated?
When contributions are made, whether mandatory for Malaysians or voluntarily for expats, they are calculated based on a percentage of your monthly salary. Both the employee and the employer contribute a portion.
The statutory contribution rate for employees is 11% of their monthly wage, while employers contribute 13% for employees earning more than RM5,000 per month, and 13% for employees earning RM5,000 or less. These rates can change over time, so it's always wise to confirm the latest figures on the official EPF website or with your HR department. For foreign workers who opt to contribute, the employee's share remains 11%, but the employer's share is a flat RM5.00 per month, regardless of salary. It's a symbolic contribution for foreign workers, really. These deductions are typically handled automatically by your employer and are remitted to the EPF on a monthly basis. This is a key part of your overall Understanding Income Tax in Malaysia: The Full Expat Guide (2027), as these contributions are eligible for certain tax reliefs.
Accessing Your EPF Funds
One of the burning questions for expats is usually, "Can I get my money back when I leave Malaysia?" The good news is, yes, you can. Unlike Malaysians, who generally can only access their full EPF savings upon reaching retirement age (currently 55 or 60, depending on the scheme), foreign workers can typically withdraw their entire EPF savings if they are permanently leaving Malaysia. This is known as a "Leaving Malaysia Withdrawal."
To do this, you'll need to provide proof of your departure, such as a cancelled employment pass, flight ticket, and a letter from your employer confirming the termination of your service. It's a process that requires a bit of paperwork and patience, as most things involving government agencies in Malaysia do. Beyond permanent departure, there are also various partial withdrawal schemes for specific purposes like buying a house, financing education, or medical expenses, although these are more commonly utilised by Malaysian citizens. Details on these can be found in our comprehensive guide, How to Withdraw Your EPF Savings When Leaving Malaysia.
Understanding SOCSO (Social Security Organisation) in Malaysia
Now, let's switch gears to SOCSO. While EPF is about long-term savings, SOCSO (Pertubuhan Keselamatan Sosial, or PERKESO in Malay) is all about immediate social protection, specifically focusing on workplace-related accidents, occupational diseases, and invalidity. It’s your safety net in case something unforeseen happens to you while on the job or affects your ability to work.
What is SOCSO and its Core Purpose?
The Social Security Organisation (SOCSO) was established under the Employees' Social Security Act 1969. Its core purpose is to provide social security protection to employees and their dependents through two main schemes: the Employment Injury Scheme and the Invalidity Scheme.
The Employment Injury Scheme provides protection for employees against accidents arising out of and in the course of employment, including occupational diseases and commuting accidents. So, if you get into an accident on your way to work, or suffer an injury at the workplace, or even contract an illness directly linked to your job, SOCSO is there to provide benefits. The Invalidity Scheme, on the other hand, provides 24-hour coverage against invalidity or death due to any cause not related to employment. This means if you become permanently incapacitated and unable to work, or if you pass away, SOCSO can provide financial assistance. This is a critical layer of protection that often goes unappreciated until it's desperately needed.
Who is Required to Contribute to SOCSO?
This is a critical distinction from EPF, especially for expats. Unlike EPF, SOCSO contributions are mandatory for ALL employees, both local and foreign, who are working in Malaysia under a contract of service or apprenticeship. This has been the case since 2019, when the Employees' Social Security Act 1969 was amended to extend coverage to foreign workers. Before that, it was a bit of a grey area, which caused a lot of confusion and left many foreign workers vulnerable.
This means that if you're working here legally, regardless of your nationality or the type of Employment Pass you hold (unless specifically exempted, which is rare), your employer must register you with SOCSO and contribute on your behalf. There's no opting in or out; it's a legal requirement. This is a crucial element for ensuring basic worker rights and protection in Malaysia, a topic often covered in guides like Understanding Malaysian Employment Contracts and Worker Rights (2027).
What Benefits Does SOCSO Provide?
SOCSO provides a range of benefits under its two schemes, designed to offer financial relief and support when an employee's ability to work is compromised.
Under the Employment Injury Scheme, benefits include:
- Medical Benefit: Free medical treatment at SOCSO panel clinics, government clinics, or hospitals.
- Temporary Disablement Benefit: Cash payments if you're temporarily unable to work due to an employment injury.
- Permanent Disablement Benefit: Compensation for permanent impairment due to an employment injury.
- Constant Attendance Allowance: For those who need a constant attendant due to severe permanent disablement.
- Dependants' Benefit: Payments to eligible dependents if an employee dies due to an employment injury.
- Funeral Benefit: Assistance for funeral expenses.
- Rehabilitation Benefit: Physical and vocational rehabilitation programmes.
The Invalidity Scheme offers:
- Invalidity Pension: A monthly payment for employees who suffer invalidity and are certified to be permanently incapacitated from earning a living.
- Invalidity Grant: A one-off payment for those who don't qualify for invalidity pension but have some contribution history.
- Constant Attendance Allowance: Similar to the employment injury scheme, for severe invalidity.
- Survivors' Pension: Monthly payments to eligible dependents upon the death of an invalidity pensioner or an insured person.
- Funeral Benefit: Also similar to the employment injury scheme.
- Rehabilitation Benefit: Physical and vocational rehabilitation.
These benefits are comprehensive and provide a vital safety net, particularly for foreign workers who might not have other forms of social protection. You can learn more about these specific protections in Understanding SOCSO Medical Benefits for Foreign Workers in Malaysia.
How are SOCSO Contributions Calculated?
SOCSO contributions are based on a tiered schedule, linked to your monthly wage. The contribution rate is typically 1.75% of your monthly wages for the employer and 0.5% for the employee under the Employment Injury Scheme. For the Invalidity Scheme, it's generally 0.5% from both employee and employer. However, for foreign workers, the contribution is entirely borne by the employer, calculated at a rate of 1.25% of your monthly wages, covering you under the Employment Injury Scheme only. This is a simplified contribution for foreign workers compared to the dual-scheme coverage for Malaysians.
There are wage ceilings for these calculations, meaning once your salary exceeds a certain amount (e.g., RM5,000 as of recent updates), the contributions are based on that ceiling, not your full higher salary. Your employer is responsible for deducting these contributions from your salary (if applicable for the employee portion) and remitting them to SOCSO. These contributions are generally quite small but provide significant coverage.
Key Differences and Why They Matter to You as an Expat
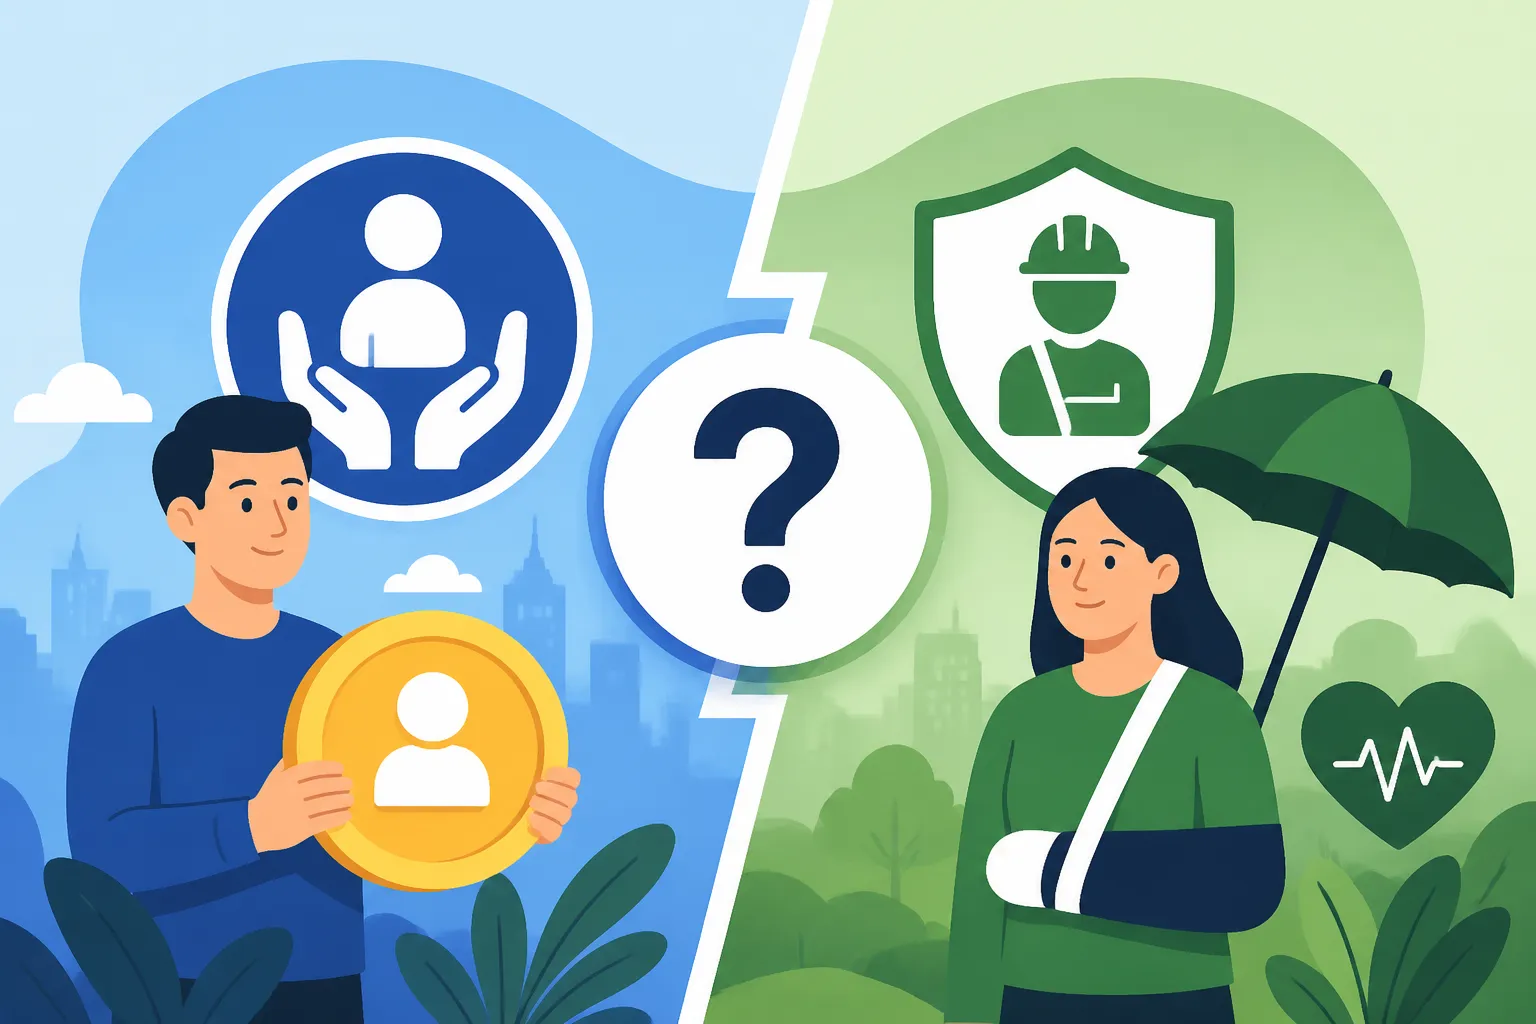
So, if you’re still feeling like it’s all a blur, let’s boil down the core distinctions between EPF and SOCSO. Understanding these differences isn't just academic; it directly impacts your financial planning, your rights, and your safety net while living and working in Malaysia.
Core Mandate and Coverage
The fundamental difference lies in their purpose:
- EPF (Employees Provident Fund): Primarily a retirement savings scheme. It’s about building up a financial nest egg for your future, with some limited pre-retirement withdrawals. It’s a long-term investment in your financial independence.
- SOCSO (Social Security Organisation): Primarily a social insurance scheme. It's about immediate protection against employment injuries, occupational diseases, and invalidity, providing cash benefits, medical care, and rehabilitation. It's your safety net for unforeseen circumstances impacting your ability to work.
One is about what you save for your future, the other is about what protects you in the present.
Contribution Requirements for Foreigners
This is perhaps the most crucial distinction for expats:
- EPF for Foreigners: Generally not mandatory. Your employer may choose to contribute, and you may choose to contribute voluntarily. If you or your employer opt-in, it becomes legally binding. Many companies use this as a competitive perk.
- SOCSO for Foreigners: Mandatory for all foreign workers under a contract of service since 2019. Your employer must register you and contribute on your behalf (with the employer bearing the full contribution for the Employment Injury Scheme). There’s no opting out. This is a critical piece of the puzzle for The Complete Guide to Working in Malaysia as a Foreigner (2027).
This mandatory aspect of SOCSO for foreign workers means that even if you're not saving for retirement through EPF, you still have essential social protection against workplace risks.
Types of Benefits
The benefits each organisation provides are vastly different, reflecting their core mandates:
- EPF Benefits: Primarily cash withdrawals of your accumulated savings, either upon retirement (for locals), permanent departure from Malaysia (for foreigners), or for specific purposes like housing or education.
- SOCSO Benefits: A range of services and payments including free medical treatment, temporary or permanent disability payments, invalidity pensions, rehabilitation, and survivor benefits for dependants. These are not withdrawals of your savings but insurance payouts.
To illustrate, consider this table comparing the two:
| Feature | Employees Provident Fund (EPF) | Social Security Organisation (SOCSO) |
|---|---|---|
| Primary Purpose | Retirement savings, long-term financial security | Social insurance, protection against employment injuries & invalidity |
| Governing Act | Employees Provident Fund Act 1991 | Employees' Social Security Act 1969 |
| Coverage (Malaysians) | Mandatory for all private sector employees | Mandatory for all private sector employees |
| Coverage (Foreigners) | Voluntary (employer/employee option) | Mandatory for all foreign workers |
| Employee Contribution | 11% (if opted in) | 0.5% (for Invalidity Scheme, if eligible) |
| Employer Contribution | 13% or RM5.00 for foreign workers (if opted in) | 1.25% (for Employment Injury Scheme, for foreign workers) |
| Main Benefits | Lump sum withdrawal upon retirement or leaving Malaysia | Medical treatment, cash benefits for injury/invalidity, rehabilitation |
| Withdrawal/Claim | Withdrawal of accumulated savings | Claiming insurance benefits based on eligibility |
| Key Distinction | Savings for future | Protection for present risks |
Navigating the Bureaucracy
Dealing with government agencies in a new country can be daunting. Both EPF and SOCSO have their own procedures and systems.
- EPF Registration: If you or your employer opt-in, your employer will handle the registration process for you. You'll then get an EPF account number and can register for online access via the i-Akaun portal to monitor your contributions.
- SOCSO Registration: Your employer is legally obligated to register you within 30 days of your employment start date. You'll be assigned a SOCSO Insured Person Number, which is usually your NRIC (for Malaysians) or your passport number. Claims are filed through your employer or directly with SOCSO.
Language can sometimes be a barrier when dealing with these systems. While official forms and most staff will have English options, understanding the finer points of regulations can be tricky. It might be a good idea to brush up on your Bahasa Malaysia phrases, especially if you're navigating certain aspects independently. Resources like iTalki can be surprisingly helpful for learning practical conversation skills that will allow you to communicate more effectively with local authorities and better understand forms.
Practical Implications for Expats in Malaysia
Understanding EPF and SOCSO isn't just about compliance; it's about making informed financial and personal well-being decisions during your time in Malaysia.
When and How Expats Contribute
As established, SOCSO is mandatory for all foreign workers. This means from your very first paycheck, your employer should be making contributions on your behalf, and you are covered under the Employment Injury Scheme. You shouldn't have to do anything proactive other than ensuring your employer has indeed registered you. It’s worth asking your HR department for confirmation and your SOCSO Insured Person Number.
For EPF, if you've opted for voluntary contributions, or your employer provides it as a benefit, these deductions will also be made automatically from your salary. You'll need to confirm with your employer what the arrangement is and ensure they provide you with your EPF account details. It's a good idea to track these contributions, especially if you plan to withdraw them when you eventually leave Malaysia. Keeping an eye on your payslips is crucial for this. If you’re also delving into other aspects of your finances, such as your tax obligations, a resource like Taxes for Expats can offer useful insights.
Claiming Benefits as a Foreigner
Claiming benefits from either EPF or SOCSO involves specific procedures:
- EPF Withdrawal: When you decide to leave Malaysia permanently, you'll initiate the "Leaving Malaysia Withdrawal" process. This involves submitting an application form, your passport, proof of termination of employment, proof of leaving the country (e.g., flight ticket, visa cancellation), and a bank statement for the fund transfer. The process can take a few weeks to a couple of months. Ensure all your documents are in order to avoid delays.
- SOCSO Claims: If you suffer an employment injury or occupational disease, the first step is to report it to your employer immediately. Your employer then has to notify SOCSO using the appropriate forms (e.g., Accident Report Form 21, Occupational Disease Report Form 34). You'll typically need to provide medical reports. SOCSO will investigate the claim and, if approved, will provide the relevant benefits. For invalidity claims, the process is more complex, usually requiring a medical examination by a Medical Board. It’s important to remember that these are not savings you withdraw, but rather claims against an insurance scheme. Our article How Do I Claim SOCSO Medical Benefits as a Foreign Worker in Malaysia? offers a step-by-step guide.
Financial Planning Beyond EPF and SOCSO
While EPF and SOCSO offer crucial financial scaffolding, especially for your working life in Malaysia, they shouldn't be your only financial plans.
- Supplementary Health Insurance: SOCSO covers employment-related medical costs, but for non-work-related illnesses or injuries, you’ll need good private health insurance. Consider international plans or local private options to ensure comprehensive coverage.
- Personal Savings and Investments: If you're not contributing to EPF, or even if you are, diversify your savings. Look into personal investment accounts, international retirement plans, or other wealth-building vehicles that align with your long-term financial goals, especially if you envision moving to other countries in the future.
- Emergency Fund: Always maintain an accessible emergency fund. Life throws curveballs, and having liquid savings separate from your EPF (which isn't instantly accessible anyway) can prevent financial stress during unexpected events.
- Understanding Your Employment Pass: Your Employment Pass dictates many aspects of your stay and work in Malaysia. Make sure you fully understand its terms and conditions, including its impact on your benefits and financial arrangements. For comprehensive details, see How to Get an Employment Pass in Malaysia (2027).
These systems are designed to offer fundamental protection and savings. Your proactive engagement with your employer, understanding your rights, and supplementing these with personal financial planning will set you up for a smoother, more secure expat journey in Malaysia.
Disclaimer
This article is for general informational purposes only and does not constitute professional advice. Laws, prices and regulations vary by location and change over time. Consult a qualified professional for guidance on your specific situation.